What’s the Difference Between Variance and Standard Deviation?
You calculate a variance and get a number in strange squared units that feels disconnected from your data. The standard deviation solves that: it is the square root of the variance, back in the original units. This guide explains how the two connect and when to report each.
How They Are Connected
The standard deviation is defined as the square root of the variance. They describe exactly the same spread, on different scales. If you know one, you can always get the other: square the standard deviation to get the variance, or take the square root of the variance to get the standard deviation.
Worked Example
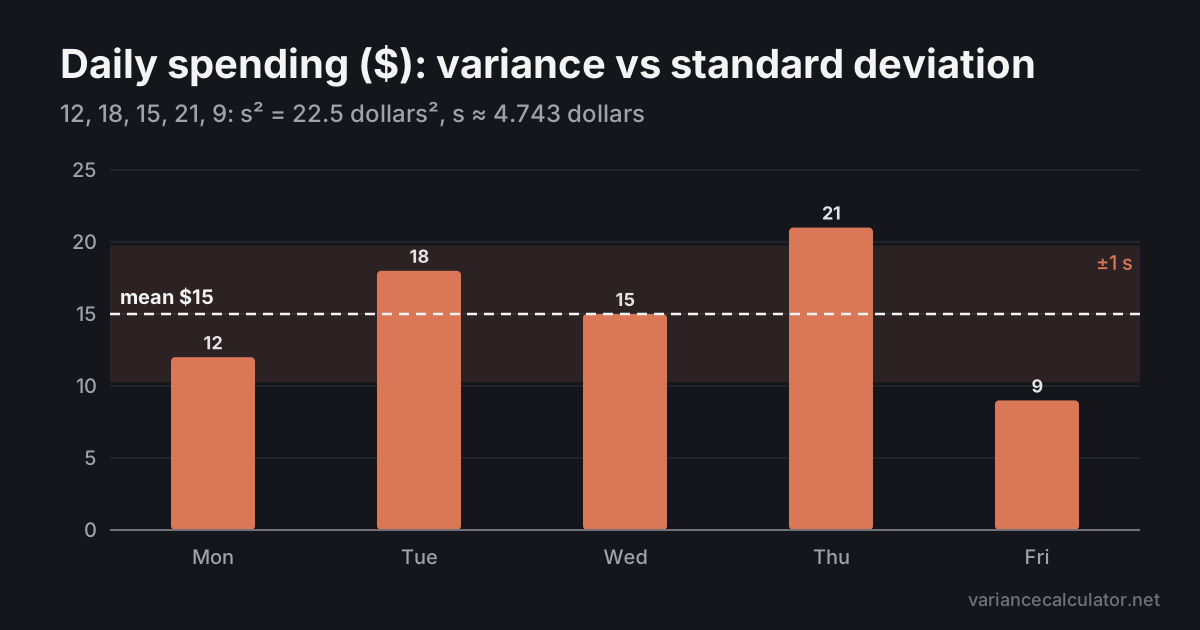
Someone records what they spend on lunch over five days: $12, $18, $15, $21, $9. Treat it as a sample of their usual spending.
- The mean is 75 / 5 = 15.
- Deviations: −3, 3, 0, 6, −6.
- Squared deviations: 9, 9, 0, 36, 36. The sum of squares is 90.
- Sample variance: s² = 90 / 4 = 22.5 dollars squared.
- Sample standard deviation: s = √22.5 ≈ 4.743 dollars.
“Lunch costs about $15, give or take about $5” is immediately meaningful. “The variance is 22.5 dollars squared” is correct, but nobody can picture a squared dollar.
Why the Units Differ
Variance squares each deviation, so it squares the units too: dollars become dollars squared, centimetres become square centimetres. Taking the square root reverses that and returns to the original units.
When to Report Standard Deviation
Use it whenever you are describing spread to people: in reports, on charts, in the “mean ± SD” format used in many tables. It is on the same scale as the data, so readers can compare it directly with the values.
When to Use Variance
Use variance when you are doing further calculations. Variances of independent quantities add (Var(X + Y) = Var(X) + Var(Y)); standard deviations do not. That is why ANOVA, regression and portfolio risk calculations work with variances, and convert to standard deviations only at the end.
Large Deviations
Squaring gives large deviations more weight than small ones. The standard deviation inherits that weighting, since it is computed from the same squared deviations, but its square root brings the final figure back to a scale that matches the data.
Sample and Population Versions
Each measure has a sample and a population version. The sample variance divides by n − 1; the sample standard deviation is simply the square root of that. The same applies to the population versions, which divide by N.
| Symbol | Meaning |
|---|---|
| σ² | Population variance |
| σ | Population standard deviation |
| s² | Sample variance |
| s | Sample standard deviation |
Summary
Variance and standard deviation are two views of the same spread, connected by a square root. Use the standard deviation to communicate and variance to calculate. The standard deviation calculator gives you both from the same data.